Tax &
Legal
Wealth
Management
Global
Mobility
Luxury Assets
& Tech
Real
Estate
Company
News
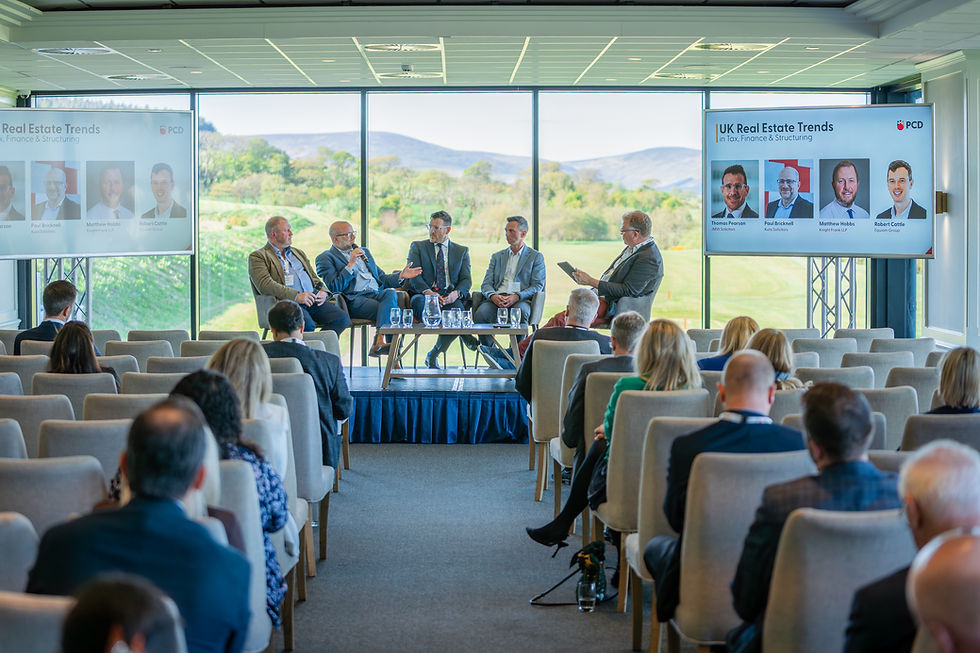
Capital, Structure and Risk: Lessons from the Jersey International Real Estate Conference
PCD Jersey International Real Estate Conference, 1 October 2026. Panels explore where UK real estate opportunity lies for private capital, how Jersey structures support it, and the operational, cyber and governance risks investors must manage.
By
PCD
Published
2 November 2026

Real estate rarely rewards the passive. That was the message running through PCD’s Jersey International Real Estate Conference, where three panels of investors, lawyers, lenders, fund specialists and asset managers took the market apart from three angles: where the opportunity lies, how to hold it, and what can go wrong. Taken together, the sessions described a market in which institutional capital is hesitant, bank lending is retreating and margins are thin, and in which well-advised private wealth has an unusual chance to step in, provided it does so with discipline.

The tone was set early. This was a discussion about opportunity, not optimism. Risk is what is holding much institutional money back across the UK, and that hesitation is precisely what creates room for private capital.
The UK is many markets, not one
The opening panel treated the UK not as a single market but as a patchwork of regions, each with its own dynamics. The single most important variable, panellists argued, is often the local authority. Much of the country’s stagnation stems from schemes caught in endless rounds of planning and viability review, so the smartest investors follow political will: places where the pressure to deliver housing or regeneration is strongest and where councils are actively offering land. Plymouth, with major defence investment and ambitious housing targets, and Cardiff, where planners have been openly courting hotel development, were cited as examples of authorities that want deals done.
Devolution is helping, but unevenly. Greater Manchester’s combined authority is on the front foot, while elsewhere a circular problem persists: public money follows only those projects that already have private capital committed, yet private capital will not commit until the viability gap is closed.

Making the numbers work
Panellists were candid that very little stacks up easily at present. With returns now driven largely by income rather than yield compression, occupier demand must lead allocation decisions. There are bright spots, notably the steady rise in Grade A office rents in regional cities such as Leeds, and the way energy-performance rules in London are pushing tired buildings towards repositioning and, ultimately, more resilient income.
For developers, viability has become a game of marginal gains: a couple of percentage points won on land, on build cost, on finance and on design, with grant funding as the final lever. Land values for some London residential schemes have fallen sharply, and direct engagement with public bodies can unlock affordable housing grant well beyond published policy levels. The trade-off is that investors and developers must accept thinner profit margins than in the past.
While plenty of domestic capital may still be ‘risk-off’ for real estate as an asset class, or for development risk generally, global capital has taken over as the main net investor into the UK, but these investors are often focusing on niche opportunities with existing trusted partners. The private overseas money that once chased broad allocations and development has slowed as the cost of construction hampers return expectations and the UK’s residential delivery has stalled far below target, although it was noted there is growing interest in single-family housing or in opportunities where viability issues are already addressed. Data centres prompted the liveliest debate: the old mantra of “beds, sheds and meds” may have become “beds, sheds and power”, but questions over exit liquidity, decommissioning and short obsolescence cycles suggest caution.
Private capital’s moment
A theme that connected all three sessions was the widening gap between what institutions and banks will do and what the market needs. Banks are stepping back from transitional real estate, and leverage has fallen just as valuations have reset. That leaves space for family offices and private investors to act as lenders as well as equity, taking on situations that mainstream finance will not touch, such as stabilising a distressed portfolio until it can be refinanced.
Operational real estate offered a template for how private capital can lead. Self-storage was once a niche, entrepreneur-driven sector; private money carried it through years of early negative cash flow before institutional investors arrived and bought in. Operators now back far smaller towns than they once would. Several panellists suggested branded, hospitality-led offices and living may be following the same path, and that hotels in carefully chosen locations, from city-centre office conversions to regional markets buoyed by tourism and energy infrastructure, illustrate a genuine stock-picker’s market.
The structure is the strategy
If the first panel asked where to invest, the second asked how. Its guiding principle was simple: the property is the asset, but the structure is the strategy. Advisers urged investors to start with their objectives rather than the vehicle. Who is the investor, how long is the hold, will partners join later, and how will the deal be financed? The answers dictate the structure.
The investor base drives much of the choice. A UK resident may sensibly use a UK company; private equity will expect a GP/LP arrangement; pension schemes, sovereign funds and many US and EU investors favour tax-transparent vehicles such as Jersey Property Unit Trusts. Development activity can turn capital gains into trading income, so blocker entities are often needed, and income strategies may suit Opco/Propco arrangements or REITs. Where Gulf capital is involved, Sharia-compliant financing structures are increasingly standard.
Jersey’s own toolkit was a recurring point of pride. This year’s company law reforms have modernised the regime, making shareholder agreements more robust and confidential and simplifying buybacks and capital reductions, while UK tax-resident Jersey companies offer stamp duty advantages on share transfers. The Jersey Private Fund was singled out as the island’s most successful structuring innovation in a decade: light-touch, quick and affordable, yet institutional in standard, and the natural home once capital is pooled beyond a simple club deal.
Above all, structure must anticipate stress. Heads of terms are the moment to settle decision-making, reserved matters, deadlock and exit. Joint ventures most often fracture when more capital is needed and one partner cannot or will not contribute. Lenders, meanwhile, want to know before a spade goes in the ground who funds a cost overrun, and borrowers should negotiate cure rights and extension options at the outset, building in more time than they think they will need. Those who remember the pre-2008 rush to set up structures quickly, with imperfect paperwork that caused real pain when markets turned, urged investors to draft tightly while they have the time.

Seeing risk before it arrives
The closing panel turned to the darker side of the opportunity. Its first lesson was scepticism: do not believe the brochure. Seasoned asset managers start with lease length and whether tenants are genuinely in occupation and trading, because an estate that looks fully let on paper can be quietly emptying. Refurbishment estimates are almost always too light, and the further up the risk curve, the more under-cooked they tend to be. Proper due diligence means more than a checklist; it means eyes on the ground and an understanding that property ownership is fundamentally about relationships with sellers, neighbours and tenants.
Risk is also increasingly digital. Property transactions, with large sums moving between multiple parties, are a rich target for criminals, and a single attack on conveyancing software has previously frozen transactions across dozens of firms. Buildings themselves are exposed, as net zero designs rely on interconnected systems controlling heating, lighting and security. Invoice fraud, phishing and deepfake impersonation are growing threats, and as clients seek greater anonymity, verifying that a counterparty is who they claim to be will matter more. Panellists recommended technical due diligence alongside structural and legal reviews, and asked boards a pointed question: what is plan B if the building’s systems go down?

Complexity carries its own danger. Over-optimistic sponsors favour elaborate structures they cannot fully explain, and treat private credit as a friend rather than a counterparty with costly reporting demands. Cross-collateralisation can allow a problem in one entity to bring down an entire group.
Protecting income and governing well
Once an asset is owned, value is protected on the ground. Asset managers described how engaged, can-do relationships with tenants, paired with targeted capital expenditure, can transform lease lengths on unremarkable regional estates within a couple of years. Speed matters: with refurbishment and green compliance costs roughly doubling since before the pandemic, a quick decision that keeps a tenant in place is often a bargain. Investors were urged to prepare for a coming “compliance cloud” around energy performance, to lengthen leases while occupiers have appetite, and to build early-warning systems through local agents who know when tenants start looking elsewhere.
Governance completes the picture. The offshore board’s role is oversight, not doing: defining what information it needs and when, with a clear escalation route for urgent decisions rather than waiting for the next quarterly meeting.
The common thread
Across all three panels, the same conclusions kept surfacing. There is no perfect structure, market or asset, only the right fit for the investor, the asset and the exit. Getting it right on day one is far cheaper than fixing it later. Assumption lies behind most mistakes, so investors should understand their “why” and surround themselves with advisers, lenders, managers and service providers who know what they are looking for.
And for all the talk of capital flows, tax transparency and cyber controls, the conversation kept returning to the same point. Institutions may demand more transparency, reporting and control than ever, but trust remains the deciding factor. Real estate is still very much a people business.